Work at Home Kit

The More You Read, The More You Learn

Why learning is important..."It is critical that a company create the kind of environment in which people really believe they can learn, grow, and prosper. The focus has to be on developing people."


Google

Thursday, May 31, 2007

Avoiding Foreclosure

If you can’t make your next mortgage payment, or if you are already behind, you need immediate help. The Homeownership Preservation Foundation has joined forces with mortgage lenders, nonprofit organizations and city government agencies to provide homeowners with assistance and resources to help you get back on track.

Visit the Hope for Homeowners website, or call the homeownership hotline at 1-888-995-HOPE for immediate assistance.

Here are a few tips from NeighborWorks for avoiding foreclosure:

* Take advantage of pre-purchase counseling or financial education offered by nonprofit organizations

* Free pre-purchase counseling is offered through local governments as well as nonprofit organizations.

* Avoid prepayment penalties and balloon payments.
People who refinance their mortgages with loans containing prepayment penalties or balloon payments are more likely to undergo foreclosure, according to a study by researchers at the University of North Carolina. According to the study, a prepayment penalty increases foreclosure risk by about 20 percent. Mortgages with balloon payments were 46 percent more likely to go to foreclosure than loans without. Protect the equity in your home – it’s a valuable source of wealth that will build over time.

* Stay on top of home repairs and maintenance. NeighborWorks organizations provide counseling in home maintenance and repairs and rehabs that improve the value of a home. Too often emergency repairs and less-than-trustworthy contractors push a homeowner into foreclosure.

What should you do if you miss a payment?
More than half of those in foreclosure did not call for help when they fell behind in their mortgage payments. Calling for help is the most important factor in preventing foreclosures.

Notify the bank as soon as you know your payment will be late. Calling when you are 30 or 60 days late is better than calling when you are 120 days late Remember that foreclosure is not in the best interest of lenders – lenders report that it costs up to $50,000 or almost half the loan balance each time they write off a foreclosure.
Work it out. Depending on the situation, the lender may lower the interest rate, lower the borrower’s monthly payment, or enter into a repayment agreement for missed payments.

What are your options if you cannot make payments?

Forbearance
– You are allowed to delay payments for a short period, with the understanding that another option will be used afterwards to bring the account current.

Reinstatement – When you are behind in your payments but can promise a lump sum to bring payments current by a specific date.

A Repayment Plan – If your account is past due, but you can now make payments, the lender may agree to let you catch up by adding a portion of the past due amount to each current monthly payment until your account is current.

Modifying Your Mortgage – The lender can modify your mortgage to extend the length of your loan (or take other steps to reduce your payments). One solution is to add the past due amount into your existing loan, financing it over a long term.

Selling Your Home – If catching up on payments is not possible, the lender might agree to put foreclosure on hold to give you some time to attempt to sell your home.

Property Give-Back – The lender can allow you to give-back your property-- and then forgive the debt. Give-backs do, however, have a negative impact on your credit record, although not as much as a foreclosure. The lender might require that you attempt to sell the house for a specific time period before agreeing to this option, and it might not be possible if there are other liens against the home.

Again, if you do fall behind on your mortgage payment, don't waste another minute, call your lender before it's too late.

Tuesday, May 29, 2007

How To Shop for a Loan

There are hundreds of mortgage lenders that will pre-qualify and pre-approve you for a mortgage loan. Don't let these two terms confuse you. See my prior post on pre-qualify/pre-approval for clarification.


Major categories of mortgage lenders include:

Savings & loans: Also called thrift institutions, savings and loan associations (S&Ls) are the largest traditional lenders of residential home mortgages.

A government cleanup of bad loans at S&Ls that ended in the 1990s left behind the stronger S&Ls. These institutions remain a major source of funding for home mortgage loans. S&Ls are often called savings banks in the eastern U.S.

Commercial banks: Commercial banks offer attractive loan terms, particularly if they evaluate their entire banking relationship with you. Some commercial banks have their own real estate departments and will service your mortgage loan.

Other commercial banks sell their mortgages to Fannie Mae and Freddie Mac, two major government-sponsored enterprises that specialize in buying residential mortgages from lenders.

Mortgage bankers: Mortgage bankers borrow money from banks or pools of investors, underwrite the loans, and sell them to investors for a profit. They often receive a fee from these investors for servicing your mortgage. Mortgage servicing includes collecting monthly payments, sending out loan statements, and collecting on late payments. For more information, see the Web site of the Mortgage Bankers Association of America (MBAA).

Mortgage brokers: Mortgage brokers circulate, or "shop," a loan application among lenders to find the most attractive terms for the borrower. In exchange, a lender pays the broker a fee.

Homeowners: The most overlooked and a financially beneficial method. You may find that the current homeowner is willing to offer financing in exchange for selling the home sooner. This means that the seller becomes your lender. A common means of financing is for the seller to accept a mortgage note. A mortgage note requires you to make monthly payments to the seller instead of a bank or other lender. See my website for add'l info: AC Associates

Credit unions: Since credit unions are owned by their members, they are called cooperative financial institutions. Since they are nonprofit institutions, credit unions may offer attractive mortgage loan rates to their members. Like commercial mortgage lenders, credit unions sell their loans to Fannie Mae and Freddie Mac to maintain access to new sources of funds. The National Credit Union Administration (NCUA) regulates the credit union industry.

Nonprofit community development and housing organizations: Throughout the United States, there are hundreds of nonprofit community-based organizations that work to rebuild neighborhoods that have fallen into disrepair, or to help low-and moderate-income families buy homes. Often, these organizations have money available from government or private grants to loan for home purchases or for home improvement loans. The interest rates are often less than the cost of bank loans and the repayment terms are easier for new homebuyers. Check with your city housing agency and ask for the names of non-profit housing groups in your area or search for local organizations that are part of national nonprofit networks, such as these:

NeighborWorks organizations: These local nonprofit housing advocates provide many services to low-income homebuyers, including homeownership training, financial counseling, foreclosure intervention, loans for rehabilitation and repair of existing properties, and, sometimes, home loans. There are hundreds of these local nonprofits nationwide. Visit www.nw.org for more information.

HUD-Approved Housing Counseling Agencies: These local nonprofit and public agencies offer rental, homeownership and foreclosure prevention counseling. They can also help you obtain mortgage financing directly from them or through referrals to local lenders. Visit HUD's website for more information.

Government Agencies:

State or Local Housing Finance Agencies: Almost every state has a housing finance agency (HFA) that works with state and local groups to revitalize neighborhoods and promote homeownership. They also provide financing for special uses, including rehabilitation of existing home. HFAs may have financing available at lower interest rates or require lower down payments and closing costs for low-and moderate-income or first-time homebuyers. City and county agencies generally perform the same function as state HFAs. Ask your local lender, real estate agent or a nonprofit housing organization about state and local government agencies. You can also visit www.ncsha.org for more information on state housing finance agencies.

Saturday, May 26, 2007

100 Quotes from "The Secret"

If YOU believe that YOU CAN and WANT to do better for Yourself...
* write that book, start that business (part time or full time), make more money, use your talents, go back to school, get a new career or job, stop settling for less than you deserve, get motivated, pursue your dreams, become motivated, confident, feel good about yourself, change your life, create the life you want and get the results you want...

1. We all work with one infinite power.
2. The Secret is the Law of Attraction (LOA).
3. Whatever is going on in your mind is what you are attracting.
4. We are like magnets - like attract like. You become AND attract what you think.
5. Every thought has a frequency. Thoughts send out a magnetic energy.
6. People think about what they don't want and attract more of the same.
7. Thought = creation. If these thoughts are attached to powerful emotions (good or bad) that speeds the creation.
8. You attract your dominant thoughts.
9. Those who speak most of illness have illness, those who speak most of prosperity have it..etc...
10. It's not "wishful" thinking.
11. You can't have a universe without the mind entering into it.
12. Choose your thoughts carefully .. you are a masterpiece of your life.
13. It's OK that thoughts don't manifest into reality immediately (if we saw a picture of an elephant and it instantly appeared, that would be too soon).
14. EVERYTHING in your life you have attracted .. accept that fact .. it's true.
15. Your thoughts cause your feelings.
16. We don't need to complicate all the "reasons" behind our emotions. It's much simpler than that. Two categories .. good feelings, bad feelings.
17. Thoughts that bring about good feelings mean you are on the right track. Thoughts that bring about bad feelings means you are not on the right track.
18. Whatever it is you are feeling is a perfect reflection of what is in the process of becoming.
19. You get exactly what you are FEELING.
20. Happy feelings will attract more happy circumstances.
21. You can begin feeling whatever you want (even if it's not there).. the universe will correspond to the nature of your song.
22. What you focus on with your thought and feeling is what you attract into your experience.
23. What you think and what you feel and what actually manifests is ALWAYS a match - no exception.
24. Shift your awareness.
25. "You create your own universe as you go along" Winston Churchill.
26. It's important to feel good ( ( ( (((good))) ) ) ).
27. You can change your emotion immediately .. by thinking of something joyful, or singing a song, or remembering a happy experience.
28. When you get the hang of this, before you know it you will KNOW you are the creator.
29. Life can and should be phenomenal .. and it will be when you consciously apply the Law of Attraction.
30. Universe will re-arrange itself accordingly.
31. Start by using this sentence for all of your wants: "I'm so happy and grateful now that.... "
32. You don't need to know HOW the universe is going to rearrange itself.
33. LOA is simply figuring out for yourself what will generate the positive feelings of having it NOW.
34. You might get an inspired thought or idea to help you move towards what you want faster.
35. The universe likes SPEED. Don't delay, don't second-guess, don't doubt.
36. When the opportunity or impulse is there .. ACT.
37. You will attract everything you require - money, people, connections.. PAY ATTENTION to what's being set in front of you.
38. You can start with nothing .. and out of nothing or no way - a WAY will be provided.
39. HOW LONG??? No rules on time .. the more aligned you are with positive feelings the quicker things happen.
40. Size is nothing to the universe (unlimited abundance if that's what you wish) We make the rules on size and time.
41. No rules according to the universe .. you provide the feelings of having it now and the universe will respond.
42. Most people offer the majority of their thought in response to what they are observing (bills in the mail, being late, having bad luck...etc..).
43. You have to find a different approach to what is through a different vantage point.
44. "All that we are is a result of what we have thought" - Buddha.
45. What can you do right now to turn your life around?? Gratitude.
46. Gratitude will bring more into our lives immediately.
47. What we think about and THANK about is what we bring about.
48. What are the things you are grateful for?? Feel the gratitude.. focus on what you have right now that you are grateful for.
49. Play the picture in your mind - focus on the end result.
50. VISUALIZE!!! Rehearse your future.
51. VISUALIZE!!! See it, feel it! This is where action begins.
52. Feel the joy .. feel the happiness).
53. An affirmative thought is 100 times more powerful than a negative one.
54. "What this power is, I cannot say. All I know is that it exists." Alexander Graham Bell.
55. Our job is not to worry about the "How". The "How" will show up out of the commitment and belief in the "what."
56. The Hows are the domain of the universe. It always knows the quickest, fastest, most harmonious way between you and your dream.
57. If you turn it over to the universe, you will be surprised and dazzled by what is delivered .. this is where magic and miracles happen.
58. Turn it over to the universe daily.. but it should never be a chore.
59. Feel exhilarated by the whole process .. high, happy, in tune.
60. The only difference between people who are really living this way is they have habituated ways of being.
61. They remember to do it all the time.
62. Create a Vision Board .. pictures of what you want to attract .. every day look at it and get into the feeling state of already having acquired these wants.
63. "Imagination is everything. It is the preview of life's coming attractions." Albert Einstein.
64. Decide what you want .. believe you can have it, believe you deserve it, believe it's possible for you.
65. Close your eyes and visualize having what you already want - and the feeling of having it already.
66. Focus on being grateful for what you have already .. enjoy it!! Then release into the universe. The universe will manifest it.
67. "Whatever the mind of man can conceive, it can achieve" W. Clement Stone.
68. Set a goal so big that if you achieved it, it would blow your mind.
69. When you have an inspired thought, you must trust it and act on it.
70. How can you become more prosperous?? INTEND IT!!
71. 'Checks are coming in the mail regularly'... or change your bank statement to whatever balance you want in there... and get behind the feeling of having it.
72. Life is meant to be abundant in ALL areas...
73. Go for the sense of inner joy and peace then all outside things appear.
74. We are the creators of our universe.
75. Relationships: Treat yourself the way you want to be treated by others .. love yourself and you will be loved.
76. Healthy respect for yourself.
77. For those you work with or interact with regularly .. get a notebook and write down positive aspects of each of those people.
78. Write down the things you like most about them (don't expect change from them). Law of attraction will not put you in the same space together if you frequencies don't match.
79. When you realize your potential to feel good, you will ask no one to be different in order for you to feel good.
80. You will free yourself from the cumbersome impossibilities of needing to control the world, your friends, your mate, your children....
81. You are the only one that creates your reality.
82. No one else can think or feel for you .. its YOU .. ONLY YOU.
83. Health: thank the universe for your own healing. Laugh, stress free happiness will keep you healthy.
84. Immune system will heal itself.
85. Parts of our bodies are replace every day, every week..etc... Within a few years we have a brand new body.
86. See yourself living in a new body. Hopeful = recovery. Happy = happier biochemistry. Stress degrades the body.
87. Remove stress from the body and the body regenerates itself. You can heal yourself.
88. Learn to become still .. and take your attention away from what you don't want, and place your attention on what you wish to experience.
89. When the voice and vision on the inside become more profound and clear than the opinions on the outside, then you have mastered your life.
90. You are not here to try to get the world to be just as you want it. You are here to create the world around you that you choose.
91. And allow the world as others choose to see it, exist as well.
92. People think that if everyone knows the power of the LOA there won't be enough to go around .. This is a lie that's been ingrained in us and makes so many greedy.
93. The truth is there is more than enough love, creative ideas, power, joy, happiness to go around.
94. All of this abundance begins to shine through a mind that is aware of it's own infinite nature. There's enough for everyone. See it. Believe it. it will show up for you.
95. So let the variety of your reality thrill you as you choose all the things you want.. get behind the good feelings of all your wants.
96. Write your script. When you see things you don't want, don't think about them, write about them, talk about them, push against them, or join groups that focus on the don't wants... remove your attention from don't wants.. and place them on do wants.
97. We are mass energy. Everything is energy. EVERYTHING.
98. Don't define yourself by your body .. it's the infinite being that's connected to everything in the universe.
99. One energy field. Our bodies have distracted us from our energy. We are the infinite field of unfolding possibilities. The creative force.
100. Are your thoughts worthy of you? If not - NOW is the time to change them. You can begin right were you are right now. Nothing matters but this moment and what you are focusing your attention on.

Source: http://www.jwaits.com

Wednesday, May 23, 2007

Turn Used Cell Phones Into CASH!


I received a postcard in the mail today from PaceButler. It explains how you can turn your used cell phones into cash. It's simple, fast, and rewarding with their used cell phone buyback program.

They've made it their goal to offer the fastest payment possible. They cut your check within 4 business days of receiving your cell phones!
Not only will you be compensated financially, but by recycling your used cell phone you are taking a stand against environmental degradation by keeping the toxic chemicals in cell phones out of landfills.
Non Profits: Raise Funds By Hosting a Used Cell Phone Drive

Fundraising is easy with their cell phone drive kit. PaceButler ensures that your organization gets a great price for used cell phones and that your payment is sent to you within 4 days of receiving your phone shipment. As a partner, you'll also be listed in the American Cell Phone Drive directory so that local residents can find your organization when seeking a drop-off center. Better yet, for every 250 phones they purchase, your organization will receive a free $50 Visa gift card to spend any way you choose.

4 Easy Steps:

1.) Use the purchase price list to find the buyback value of your phones.
2.) Request a free FedEx pre-paid shipping label so they can pay the shipping.
3.) Box up your phone handsets and batteries (no accessories, chargers, etc.) then ship with their pre-paid label.
4.) Get Cash! They'll issue your check within 4 business days of receiving your cell phones

Here's a chance to make a few dollars instead of your old cell phones taking up space. I know mine are!

Sunday, May 20, 2007

Test Your Financial Fitness


Answer the following questions to the best of your ability. Once completed, tabulate your answers to find out about your financial educational needs.
Questions:
1)
Late payments on bills are a major problem and can lead to a denial of credit when seeking a loan.
True False Not Sure

2) You should keep enough in your savings account to cover three months of living expenses.
True False Not Sure

3) No more than 25 percent of your income should be used to pay off debts that require at least 10 months of payment before the debt is fully repaid.
True False Not Sure

4) If you don’t have enough money to pay your bills, you should call your creditors right away and tell them.
True False Not Sure

5) A bankruptcy will stay on your credit report for 7 to 10 years.
True False Not Sure

6) The lowest interest rate on a loan doesn’t always mean the best loan.
True False Not Sure

7) Banks are not required to provide customers the best, most competitive rate based on their credit score and financial means.
True False Not Sure

8) When you use a credit card, you are borrowing money from a bank.
True False Not Sure

9) The practice of keeping your ATM receipts is not a sufficient means of financial management.
True False Not Sure

10) Your credit history has an effect on your ability to get a job or rent an apartment.
True False Not Sure

Get the answers here:

Friday, May 18, 2007

Pre-Approved or Pre-Qualified?

Don't Confuse "Pre-Approved" and "Pre-Qualified" with a Loan Commitment:

These are debatable terms in real estate because not all lenders apply the same definition to each term. I have learned that one leading real estate dictionary contains neither expression because their definitions are uncertain.

According to one school of thought, when you are "pre-qualified," the lender is making an educated guess about how much you can borrow based on information you've provided. When you are "pre-approved," the lender has verified everything you have told him or her and is offering to lend you up to a given amount at current interest rates -- under certain conditions.

Whether pre-qualified or pre-approved, final clearance and a check at closing -- a loan commitment -- are subject to an appraisal satisfactory to the lender, good title, a last-minute credit check, and other verifications. When meeting with lenders, always ask how they define each term and what additional steps will be required to obtain a loan.

Wednesday, May 16, 2007

Dress Up Your Porch for Under $100

Spring is here and it’s a good time to put out the welcome mat. Your front door and porch area is an invitation to guests and it also says a lot about you.

Photo Sharing and Video Hosting at Photobucket

Here are five ways to add personality to the porch for less than $100:

Paint Adds Pop
If there’s one thing that says spring, it’s color. Painting the front door is the easiest and least expensive way to dress up your entry. But before running to the paint store for a gallon of fuchsia, look at your home’s existing color palette
.
Dark colors draw more attention ,but extreme contrasts will detract from details, so it’s important to stay in the same color family. That doesn’t mean if your house is beige, you’re stuck with only browns.
Visit a paint store to see brochures of recommended palettes using your existing colors. Also, most paint companies offer color palettes and advice online.
A good quality exterior semi-gloss enamel costs about $15 a quart. Don’t forget to sand the door before painting, just enough to remove the enamel’s gloss finish, or the paint will eventually peel.

Pottery
Regardless of the size of your entry, pottery is always a good choice to direct visitors to your front door. Depending on the size of the porch, a large single pot or a group of three smaller pots (vary the size) will look best. Make sure to coordinate the color of the pots with your front door. They don’t need to be the same color, but keeping them in the same family, as with paint selection, will create a striking look.
The least expensive pots are plastic, which look fine from a distance but aren’t always as charming close up. Ceramic pots are the most expensive, about $25 to $50 for a 12-inch pot. Fiberglass can look as appealing, even up close, and are around $10 to $20 for 10 to 13 inches.
A good choice is the venerable terra cotta, which can be easily painted to work with your scheme. A large 16-inch terra cotta pot is about $16. A 12-inch pot is about $6.50. Make sure to use a sealer to coat the inside or moisture will cause the paint to peel. Use an outdoor-rated paint, such as Patio Paint, which comes in a large variety of colors and costs about $5 for an 8 oz. bottle and $1.75 for 2 oz.

Flowers / Plants
This will also give your front porch some needed curb appeal. Even if you don’t use a pot, place a couple of six-packs of bright flowers in front of or along your porch. Keep in mind your color scheme. You probably don’t want orange mums if you are using blues or lavenders.
A one-gallon plant costs about $4 to $5. If you are using pots, use a larger plant as a centerpiece and surround it with quart or six-pack varieties.

Add a Personal Touch
An inexpensive way to add a personal touch is with a doorbell cover. These come in many sizes and styles, from golfers to lighthouses. A nice brass cover with a pineapple — the universal sign of hospitality — and the word "Welcome" above it online for $14. Expect to spend up to $20 for a nice brass doorbell cover.
If you don’t have a doorbell, consider a door knocker. These also come in many styles for around $20.

House Numbers
Replace tired house numbers with new ones in bright brass, antique brass, chrome or black Prices run about $6 each for 4- or 6-inch numbers. There are many online sites that offer a large selection of specialized font styles at around $11 each.

Other ways to enhance your entry include light fixtures, door kick plates or mailboxes.
Light fixtures can be expensive, but you can find a nice light fixture that isn't very costly. Door kick plates in various finishes are $20 to $30 depending on size and material. A simple mailbox in black or white will run $10 to $20.

Sunday, May 13, 2007

3 Simple Ways to Add Value To Your Home

"Families that spent more on home improvements also realize the greatest rates of price appreciation," the Harvard Joint Center study said. "In many regions of the country, homeowners recover as much as 80% to 90% of the cost of home improvements in the form of higher home values. Little wonder, then, that homeowners spent almost $2,300 on average in 2001 to help protect and improve their most important financial asset."


If you're getting ready to sell a house, you want to be among the homeowners who recover 80% or more of their investments in the form of a higher price. The key is thinking like a buyer. And what do buyers do? They drive up to a house and look at it. If they're not repelled by what they see, they step inside and look around.

1) Spend money on what can be seen vs. what can't be seen.
2) Fix up the exterior first, then the interior.
3) Focus first on the "Yikes!" appeal -- clutter, trash and bad smells that drive down a home's value.

The improvements that are most visible are the things you need to focus on.

Do a mini-remodel. Transform the look of your home with paint. It sounds simple, but it works! A fresh coat of paint can make your home look clean and fresh. Color and accessories can change a room's mood.

What color works best for your personality?
Black: You likely proceed with caution when faced with sudden changes and exercise restraint when making decisions.

White: Rational people who rely on their analytical powers and objectivity to solve problems. It helps you free your mind to pursue new options.

Brown: Earthy and sensual. Helps you feel comfortable and secure. It encourages authenticity and living in the moment.

Red: Is fiery, energetic and bold, with a sense of urgency. Self-confident and likes to take risks.

Green: Is natural healing and refreshing. You like to solve problems with a fresh perspective and a dose of quick witted humor.

Blue: You're a steady, stable and compassionate person with a devotion to those you love.

Purple: You rely on your keen intuition to guide you through life's challenges. Others find you mysterious and maybe even psychic.

Pink: Playful, innocent, flirty and fun. Romantics love pale pink. Dynamic personalities go for shock value and like the hotter shades.

Orange: An intense color that appeal to your serious side. You are a ethical decision maker who takes pride in achieving your goals.

Yellow: Your outlook on life is sunny, hopeful and bright. You have a spontaneous and cheery nature that others find inspiring.

The following site Benjaminmoore offers a Paint Calculator. Use this to determine how much paint you'll need for the Exterior of your house or any room(s) within your home. You don't want to get stuck with too much or too little paint.
There is a Personal Color Viewer which is also very useful. Chose the color and the animated room viewer will show you how it will look on the walls. This is a great tool.

*You may have to register to use these tools, but it's free and so worth it. I'm sure you'll visit the site many times for varies home projects.

Thursday, May 10, 2007

Another Important Figure You Should Know

When applying for a loan, mortgage loan or other types of credit, Lenders use your debt-to-income ratio (how much you owe on credit cards and loans compared with how much you earn) to help evaluate your creditworthiness.

How You Can Figure Your Debt To Income Ratio:

1) Add up your total net monthly income. This includes your monthly wages and any overtime, commissions or bonuses that are guaranteed; plus alimony payment received, if applicable. If your income varies, figure the monthly average for the past two years. Include any monies earned from rentals or any other additional income.

2) Add up your monthly debt obligations. This includes all of your credit card bills, loan and mortgage payments. Make sure to include your monthly rent payments if you rent.

3) Divide your total monthly debt obligations by your total monthly income. This is your total debt-to-income ratio.

4) Take action if your ratio is higher than 0.36, which industry professionals would call a score of 36. The lower the better. Any score higher than 36 may cause an increase in the interest rate or the down payment on a loan you apply for.

Tips :
When you total your monthly debts, use the minimum payment on your statements.
When calculating your income, a lender will only consider money from a job that you've been at for at least two years.
Unreported earned income cannot be used in the calculation.

Tuesday, May 8, 2007

Know Your Loan-to-Value Ratio

Your loan-to-value ratio is something you should know. It's an important figure when getting or refinancing a loan or requesting the removal of private mortgage insurance (PMI).

Here's how you can figure it out.

If You Are in the Process of Getting a Loan:

1) Start with the purchase price of the property as the value for the property. (I'll use the amount $150,000 as an example.)

2) Subtract the amount of your down payment ($20,000 in this example).

3) Identify your loan amount (the purchase price minus the down payment; in this case $130,000.)

4) Divide loan amount (loan) by the purchase price (value). In this example, it would be $130,000 divided by $150,000, which equals 0.87, or 87 percent - your ratio.

5) Use this number with your lender when referring to your loan. You would say that you want a loan with an 87 percent Loan-to-Value or LTV.


**Most loans with an LTV over 80 percent require PMI.


If You Already Have a Loan:

1) Get an appraisal of your property. Once you own a home, this is the only way to get an accurate assessment of its value. (If you are just doing this for information purposes, you can save the appraisal fee and simply estimate the value by comparing your property to similar homes in your neighborhood that have sold. This will be the value number for the equation.)

2) Look on your most recent loan statement to find out how much you owe (your balance). This will be the loan number for the equation.

3) Divide the loan figure by the value figure. This is your ratio.

**If you request the removal of PMI, you'll have to provide an appraisal. In removing PMI, you may request in writing to your current lender that the PMI be removed if the ratio is 80 percent or less. If you request an appraisal and the value isn't high enough, you will still pay for the appraisal.


More on Loan-to-Value (From Wikipedia)

Monday, May 7, 2007

Do You SQUIDOO??

Check out my lens

If many of you are not yet aware of Squidoo, I recommend the site. There is no cost to join.

This will even increase traffic to your Blog(s) and/or Website(s).
I personally have 4 lenses and I assure you, I've seen an increase in traffic to my Blog and Business Website. You can see all my lenses by clicking here.

I have been fortunate to read some great blogs lately. Many of you have great content, ideas and information. Spread your word!

At Squidoo, you make your own "lens" which is a one page website. You can get as detailed as you want: do marketing and advertising, get creative on a subject that interests you, spread your knowledge on a topic you want to share...the possibilities are endless.

More about squidoo, click here
(Click on "about squidoo" bottom left of page)

Squidoo is home to tens of thousands of everyday enthusiasts. Spread your ideas, make yourself known, meet new traffic. (You could even earn a royalty). What's your topic? It's FREE to make a lens.

126214 Lenses and Counting!

Saturday, May 5, 2007

Gardening: Poisonous Trees & Plants for Dogs/Cats/Humans

This time of year brings most of us outside to enjoy the warmth and sunshine. We are now doing outdoor house projects and working in our yards: weeding, planting, raking etc. Perhaps you are getting your house ready for a "Open House" or creating more "Curb Appeal" but,

If you are a dog owner like myself, I should point out that when you're deciding on what trees and/or plants to plant in your yard, BEWARE of what is poisonous to your dog.
Also, certain Household plants can also be very harmful.
Photo Sharing and Video Hosting at Photobucket

See Below For Names and Symptoms~

TREES & VINES and SYMPTOMS:

Apple (stem and leaves)
shock, mouth inflammation, rapid increase in breathing
Yew(American, English, Western)
Diarrhea, vomiting, abdominal pain
Apricot
Diarrhea, vomiting, abdominal pain
Almond
Diarrhea, vomiting, abdominal pain
Peach
Diarrhea, vomiting, abdominal pain
Wild Cherry
Diarrhea, vomiting, abdominal pain
Japanese Plum
Diarrhea, vomiting, abdominal pain
Ficus (Cuban Laurel)
stomach upset
Cherry
rapid breathing, shock, mouth irritation, increased heart rate
Balsam Pear
Diarrhea, vomiting, abdominal pain
Ficus Lyrata (Fiddle-Leaf)
stomach upset, irritated skin
Oak
Varied effects
Philodendron
(Devil's Ivy) upset stomach, convulsions, asphyxiation, death
English Ivy s
stomach upset, hyperactivity, labored breath, drooling, fever, thirst increase, pupil dilation,
staggering
Jasmine
convulsions, death
Vine
pupil dilation, upset stomach, drooling, heart failure
Matrimony Vine
varied effects
Virginia Creeper
varied effects

HOUSEPLANTS and SYMPTOMS:

Asparagus Fern
vomiting, respiratory problems, kidney failure, tremors, abdominal pain
Caladium
mouth irritation, stomach upset, asphyxiation, tremors, seizures, death
Colocasia (Elephant's Ear)
mouth irritation, stomach upset, asphyxiation, tremors, seizures, death
Deiffenbachia (Dumb Cane)
mouth irritation, stomach upset, asphyxiation, tremors, seizures, death
Philodendron (Saddle Leaf, Split Leaf)
Mouth swelling, irritation
Poinsettia
mouth irritation, stomach upset
Mum (Pot and Spider)
Skin irritation
Umbrella Plant
vomiting, respiratory problems, kidney failure, tremors, abdominal pain
Aloe Vera
diarrhea
Mistletoe
Varied effects

Plant Fertilizer: Fertilizers are dangerous to pets, if ingested.
Store these in plastic bags and in a place where it is inaccessible to your pets.

Plants Poisonous to Cats

Plants Poisonous to HUMANS


Source: About Dogs

Animal Poison Control Center 1-888-426-4435

Digg!

FSBO: Tips For Pricing Your Home


Ok, so you've decided to sell your home yourself. Congratulations! A method that will save you money. Although there is an additional sales strategy I teach that you can use as a "For Sale By Owner", but I will leave that for another post.

Right now I want to give you 4 tips on pricing your home. These are effective ways to arrive at a fair price.

1) Have 2 or 3 real estate agents analyze the value of your home. Have the agents compare this with similar homes that have sold recently in your area. The average selling price can determine the value of your home. Most agents offer this service for "free" because they want listings. Be Honest when you approach an agent. Explain that you're thinking about selling your home. You're trying to get a feel for what the market is like at this time. Of course the agent will want to list your home. Advise them you are not ready to do that at the moment.

2) Have an independent appraiser calculate the value of your home. There is a cost involved with this method. Between $175 to over $600 depending on who you use. An appraisal by an independent can be more accurate because they're not competing for a listing.

3) Simply go down the street, drive around your own neighborhood and check out the homes that have sold recently. Explain to the owners that you're going to sell your house and you're trying to determine the market value. Ask them if they would mind telling you the purchase price. Most will tell you.
If they don't want to say, you can always go to the county court house with the addresses of the homes that sold. It's public information, so you can get the information in the land records or tax assessor's office. Most public information is now available all on the Internet. Call the court house and ask for their web address. This will save you a trip to the court house and be less time consuming.


4) Another way to establish a top dollar price is to advertise for the best reasonable offer This is a great method because it really produces a spirit of competition among home buyers.
When you start to promote your home for sale and are using a newspaper ad, don't put a sales price in your ad.
List as: For Best Reasonable Offer. Deadline for offers July 8th or whatever date you wish.
The deadline does 2 things:
a) you get fast sales action
b) it tells the home buyer that they better move or they'll lose the deal

This is a powerful technique for getting the highest price for your home. Plus, create competition, which produces sales action.
Feel free to contact me if you have any questions or want additional information. I look forward to helping Home Owners DIY and be successful !

Tuesday, May 1, 2007

Free Webmaster Tools

I received an email regarding the "Submit Express" site and after checking it out, I thought it might be useful to someone who wants to Optimize their website. I found all these Free Webmaster Tools extremely helpful.


FREE SUBMISSION: Free Submission to 40+ Search Engines

META TAGS ANALYZER: Check your keyword density, receive ranking advice, check webpage load time

LINK POPULARITY CHECK: Check the number of links to your site.

KEYWORD SUGGESTION TOOL: Find additional keywords for your website.

TRAFFIC ESTIMATION TOOL: See the estimated traffic for keywords.

META TAGS GENERATOR: Generate Meta Tags for better rankings

PAGERANK CHECKER (Sponsored Link): Multi data center PR checker.

PAGE SNOOPER: HTML Source Code Viewer. See how search engines will see your site.

Sunday, April 29, 2007

How To Remove Negative Credit Yourself


The following tips will help correct your credit and it should be done with all Credit Bureaus.

I have personally used these methods and had much success removing negative items, collection accounts that were not mine and removing errors contained in my credit report.

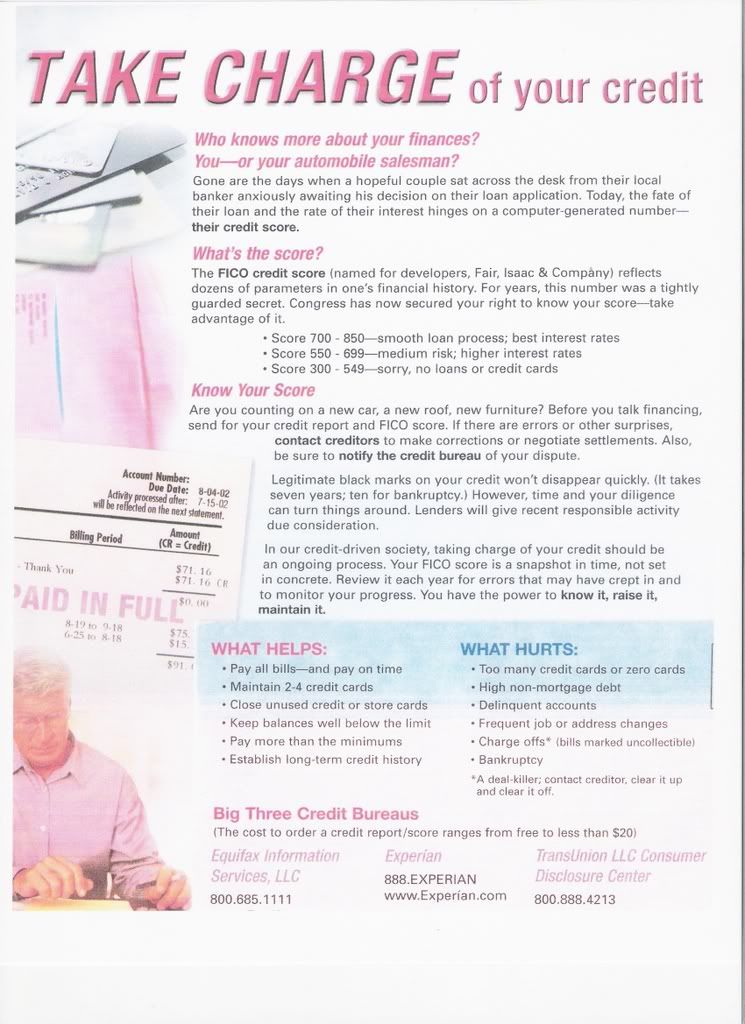
You are legally able to obtain a FREE credit report every 12 months by calling each Credit Bureau and requesting a copy of your report. If you were turned down for credit, you can request a copy of your credit report and have the company that declined you outline why you were turned down for credit.

I will show you ways of removing negative items from your credit file. These methods are sometimes referred to as "Credit Repair".

These are the exact same methods credit repair clinics and attorneys charge up to $3,500 or more to perform. Since they don't always do it correctly, people have been taken for millions of dollars over the past years.

You can outsmart creditors who are damaging your credit!

What the Credit Bureaus Don't Tell You
1. Each item on your credit report must be proven or it cannot remain in the report. If the credit bureau cannot verify the item when investigated, it must be removed from your file whether or not it's true.
2. Every negative entry on your report can be denied or challenged at any time. The bureau must reinvestigate and if that item cannot be verified within a "reasonable amount of time", it must be removed from the file.
3. Items when challenged can be mistakenly erased. Consumers say they often experience computer operator mistakes.
4. Many times the creditor does not re-verify in time or the credit bureau is busy and does not handle your dispute properly. It must then be deleted.
5. The older an item, the more difficult re-verification is. It is possible it cannot be verified because records may no longer exist after 1 or 2 years.

Steps to Repair Your Credit
1. Obtain your three credit reports.
2. Review the reports and locate the negative items.
3. Dispute the negative items with the credit bureaus.
4. Disputed items are removed or corrected. Items that were not re-verified are removed.
5. Negotiate with creditors and collection companies.
6. After negotiating and making payment, creditors delete the negative accounts or change them to a positive rating.
7. State the item you are disputing, but do not use dispute forms or file numbers provided by the bureau. This will cause fewer delays by the credit bureau asking for clarification.
8. Do not confirm the account if any information about the item is wrong.
9. Do not use letterhead (you don't want to raise any Red Flags).
10. Do not photocopy a fill in the blanks form letter (another Red Flag).
11. Send disputes during busy times of the year. For Example: The first to middle of November can cause a delay in verification because of the Thanksgiving/Christmas rush for the creditor and the bureau can catch them before they can thoroughly investigate within a reasonable time.

Please Click Here to read more in depth details on my SquidooLens: How To Remove Negative Credit Yourself


Get Your Equifax Credit Report Now!


Digg!

Saturday, April 28, 2007

"As One Door Closes, Another Door Opens"

I've always believed that when "one door closes, another door opens" ....
This past Wednesday, I had to use this phrase and try to persuade my brother into believing it too.

My brother, Mark Carangelo, LMT, NMT is the head administrator, director and owner of The American Institute of Alternative Medicine . Mark has over ten years of neuromuscular therapy teaching experience and clinical experience treating patients with various acute and chronic pain syndromes. He has extensive personalized training experience with the Aaron Mattes flexibility training program. His school is housed in a professional building where classrooms and practice rooms contain state of the art massage tables and a wide range of anatomical charts, skeletal and muscle models and various teaching aides. There is a library of books, periodicals and videos containing a wide range of massage therapy, anatomy, neuromuscular and flexibility training topics.

On Wednesday, I received a call from Mark (saying through tears) that his school building was burning down and he was in a fire. The fear and unimaginable thoughts that went through my head as I frantically raced out of my office to get to him.

Within 10 minutes, I arrived at the scene. My heart pounding out of my chest. The road was blocked and I had no where to park my car. I just wanted to park and get to him. I noticed a driveway and said to the people watching the burning building, ...." let me park here, my brother's in that building". I just left my car. I ran towards the building engulfed in flames. A few police officers tried stopping me as did two firemen, but I continued running until I got as close as I could to find my brother. After what felt like an hour, I finally found him walking away from the building. THANK GOD! In a short time we found out No one was hurt. How amazing

I've never before witnessed a raging fire that destroys in seconds. We stood there watching in disbelief. The sadness we felt to watch as everything you worked so hard for, be lost.
The firemen who responded did a tremendous job in putting out this 4 alarm fire.

As I stood there, I thought about all the people whose lives are touched by tragic fire or storm related events. How they must have felt if they lost their homes, their possessions or more importantly, loved ones. The excruciating pain and heaviness in their hearts. How sad I felt....my heart goes out to all those people.

We were lucky. My brother wasn't hurt. Possessions can be replaced. This event will make him stronger. A new door has opened and it will be a new beginning as he establishes his school in a new location.

I have personally experienced humanity as people come forward to help. There are good people in this world and it really is an uplifting feeling.

  • To the Firemen who worked so hard and did a fantastic job controlling this fire in such a short time...
  • To the people of ARCHER PLUMBING, who left a note on my car stating I could keep my car there as long as needed and wished my brother well...
  • To the many others who offered their help
  • To my brothers' previous graduates who offered supplies, equipment etc, so he can return to teaching his current students as quickly as possible....
I THANK YOU from the bottom of my heart.
"Thank you" seems like such a small word in comparison , but it is truly meant and your acts of thoughtfulness and kindness are appreciated beyond words.

Has any of my readers experienced a true act of kindness? Please post a comment. It would be nice to hear good, uplifting stories and share them with others.


Digg!

Monday, April 23, 2007

Coping With Grief - Losing a Loved One

Moving away from my usual topics, I felt compelled to write about grief and how you can cope when experiencing a loss.
Maybe this will touch someone at just the right moment or help someone during a time that is very sad, stressful, confusing or overwhelming.

Losing a loved one can be one of the most difficult and stressful experience we ever face in our lives. Yet an experience we all, unfortunately, will have to face and cope with at some point in our lives.

My family experienced the loss of a loved one on April 16th. Our loss was not of violence as many experienced that very same day, but the loss of a loved one is the most traumatic experience you have to cope with.

When death comes we do not really know what to do, where to go or who we are now. Everything changes. We all know that one day we all must leave our physical form, leave this earth, but yet we are all still unprepared for our death or that of a loved one.

Then again, how can anyone be prepared ?

Loss can include the break-up of a relationship, a miscarriage, the termination of pregnancy, separation from family and friends (homesickness), loss of health, moving.
Other forms of loss can still touch us so profoundly, such as the death of a pet or if you happen to be a medical or nursing student, you may have experienced feelings of loss when a patient dies.

With loss comes a strong feeling that part of our emotional world has changed forever and can never be retrieved or made good. Loss is central to our lives.

It is often through brokeness and loss that we truly grow into our humanity and develop the compassion that connects us to others. Following loss of any kind we go through a period of adjustment. This time and process is called grieving. It`s important to remember that grief is natural and necessary. Though the range and intensity of grief may come as a surprise, it is an entirely normal process that has been with us since the beginning of time. And, of course, as we adjust and the bits of our emotional life start to settle into a new pattern, the grief gently recedes.

Just as scar tissue is said to be stronger than the surrounding skin, so does our grieving often lead us to a state of greater resilience where we are more able to deal with future adversity.

CLICK HERE to continue reading more in depth details on my Squidoo Lens: How To Cope With Grief

Digg!

Saturday, April 21, 2007

For Sale By Owner Checklist

I've given you the definition of what a For Sale By Owner is. I've given you tips on How To Get Your Home Ready to Sell and suggested using MLS Listings as a way to get your home advertised.
Now, I think I should give you the "Seller's Checklist", so you are prepared for the upcoming sale of your home. Selling your home can be a stressful time, so if you are prepared, it will be much easier to deal with this event.

SELLER'S CHECKLIST:
o Price your house properly: You could hire an independent appraiser or receive a free appraisal from a Real Estate Agent. Most agents offer this service for free because they want listings. Be honest when you approach an agent. Explain that you are thinking about selling your home and you're trying to get a feel for what the market is like at this time.
o Advertise Your Home: Generate traffic by classified ads in local paper, weekly shoppers and/or other weekly publications, online listings. Splurge on a sign for your front yard. And don't forget - Word of mouth.
o Be mindful of the Fair Housing Act:Title VIII of the Civil Rights Act of 1968 (Fair Housing Act), as amended, prohibits discrimination in the sale, rental and financing of dwellings, and in other housing-related transactions, based on race, color, national origin, religion, sex, familial status (including children under the age of 18 living with parents or legal custodians, pregnant women, and people securing custody of children under the age of 18) and handicap (disability).
o When Brokers call: You may get calls from local agents trying to convince you that you need to list your house. They may say they have a prospect that's dying to see your property. Remember: if you allow an agent to show your house, you may be liable for his or her commission, even though you haven't signed a listing agreement.You could request your Attorney to draw up a one time only open listing agreement. Seek your attorney's advice.
o Closing the deal when offering Owner Financing: Gathering the necessary paperwork:

  1. Employment Information
  2. References
  3. banking-Financial Statement
  4. Incorporating a Balloon Payment - usually 5-10 years
  5. A good down payment: Make sure your buyer will invest some of their own money. This will also show commitment on the pat of the buyer.
  6. The credit of the payer

Keep in mind you want the strongest qualified buyer if you chose to offer Owner Financing.
The interest on your note: can be 1 to 1.5 above traditional home loans, but can be negotiable so you don't loose the sale. Based on circumstances: if the buyer is putting down 20-30%, he/she would have a lower interest rate.

  • Get Your House Ready To Sell: Before you start to promote your home, give it a thorough cleaning.
  • Give the landscape a good manicure.
  • Curb Appeal is going to make the buyer want to go inside.
  • Clean out the garage, attic, basement and all closets.
  • Hold a yard sale to get rid of unwanted items.
  • Make sure the house has a clean fresh smell in every room. Even the closets. Open the windows and air things out.
  • Make minor repairs.
  • The front of your home is where the first impression is made. Make sure the drive-way is clean and free from oil spots. Eliminate moss or mildew build-up on the front steps. The hardware on your front door should sparkle. Take care of paint that's peeling. Add a little color to the porch with a basket of flowers. A nice door mat also makes the front door look appealing.The entry area will also create first impressions.
  • Repair scratches in wood floors or worn spots in carpets.
  • Be sure to have the entry closet clean and free of clutter.
  • Put high wattage light bulbs in all fixtures and turn them on when you show the home.
  • Keep the drapes open so that everything is well lit. Dark areas can send out a bad message. People may think you're trying to hide something.
  • If you have rooms painted in dark colors change them to light colors, such as an off white. Lighter colors create an open look.
  • Put away all the personal possessions and let the buyer see how much room there really is. Personal family heirlooms can make the home look like a museum. The buyer needs to have a clear picture how their belongings are going to fit in the house.
  • Remove unnecessary furniture. The more furniture in the room the smaller it looks.
  • Get The Word Out:The first thing to do is put up a sign in the front yard. Tell your neighbors. They may already know of someone looking in the area, maybe even a family member. Let people know where you work, a church group or club. If you want to go further, put up notices on bulletin boards.
  • Run a classified ad.
  • Showing Your Home:When you have an appointment to show your home, open the windows and air out before any potential buyer arrives. This will get rid of any last minute unpleasant odors that might be lingering. It's always a good idea to have the scent of pleasant aromas in the house. Things like fresh bread,cookies, the smell of cinnamon or vanilla.
  • Open House: An open house can be very effective in promoting your house.

For Two reasons: 1) You can schedule the open house at a specific time and day and you'll be attracting a lot of people at the same time. 2)This creates a spirit of competition. Competition produces action that ends up with a sale.

  • Place a welcome sign in your front yard or by the front door.
  • For security reasons, I would recommend having visitors sign in before they go through your home.
  • Have a information circular or flyer on your home that visitors can take with them. The information flyer is good for people who call on your newspaper ad. You can take their address and even mail one to them.The information flyer should include: Your name, address and phone number. Sales Price and if you're offering OWNER FINANCING,the down payment you're requesting. Mention you'll consider all offers in writing, with the understanding you won't take the home off the market until a legally binding sales contract has been signed and earnest deposit money is deposited with your attorney.
  • Respond to all offers and if they are too low, counter the offer.Your information flyer should also include:Property taxes, insurance and utilities etc..and remember to list the features of your house:Square footage, type of roof and age, kind of heat, air conditioning, schools, kind of water heater and age, the lot size, describe the structure, electrical system, bathrooms and kitchen, the rooms size and measurements and public transportation available.Tell a little about the outdoor features and anything else you feel is unique about the home.List any recent repairs or maintenance. When was it last painted or sided, new roof etc.
  • Have pictures on display during different seasons of the year. If you're showing your home during the fall or winter, show pictures during spring or summer. The pictures will show the flowers and plants in bloom. Schedule your open house during peak hours when traffic goes by your house.
  • Put a sign up where people will see your sign as they drive by.

These tips may take some time, but in the end, you will see the reward.

Please contact me with any questions or concerns you may have.
I am here to help you.

Wishing you much success!


Digg!

Thursday, April 12, 2007

Have you heard about MY BLOG LOG ?

I discovered this site, My Blog Log about a month ago and already have met some very nice people.
This is a place where Authors and readers of Blogs have the opportunity to get to know eachother. Become friends, share ideas, promote or simply enjoy reading blogs.
Check it out....you'll be glad you did.

I had the opportunity of meeting Halil. He will be launching a new blog.."Peopleized". He wants to bring more people together by way of interviews. What a great idea! You can sign up to get updated and learn more about this interview process.

He requested an interview from me and I want to share it with my readers, so you can learn more about me.
See Below:

Hello Andrea ,

Here are a few questions about you and your blog "AC Associates Blog"
If you use url`s please write it in html if it is possible.


Before we start please some further information.

Send me a few notes on your backround: name, age, where you`re from, etc....
Andrea
48
New Jersey

Let`s Start !


1. When did you have the idea to start blogging ?
I thought about blogging after my website went “live”. I figured it was another way to get the word out about my business, help as many Home Owners as I can and maybe other people as well.
I love when I’m able to help and educate someone and a Home Owner successfully sells their home and receives an all cash sale. A win-win situation is very rewarding for all involved.

2. Would you like to share with us the url of your first post?
My first post was actually regarding Google Adsense. Joel Comm had helped me when I was first developing my web site. His tips and information was what I needed to have everything come together. I thought with the popularity of Google Adsense and Joel Comm’s tips, I should bring it to the attention of others. The low cost of $7 to obtain his e-booklet was well worth it.
http://acassociatesusa.blogspot.com/2007/03/how-i-learned-about-adsense.html

3. What is your motivation to continue blogging ?
I’d like to share knowledge and helpful tips and maybe a topic of interest to others. I’m the type of person that really enjoys helping others. I’d be lying if I didn’t include bringing attention and traffic to my sites.

4. Where did you get your daily blog inspiration from?
Since I’m a newbie to blogging, what few posts I have are about just what I know, have learned or what I care about. I’m a Home Owner and a DIY’er. I want others to know it’s easy to do things on your own when you have the knowledge. Whether that includes selling your house, doing a project around the house, learning how to pay off your mortgage in less time etc…I want to bring varied posts to people that pertains to daily life or something I think someone might benefit from.
I look at it like this: what I might be interested in or can learn from. I’m sure in time I’ll include posts that pertain to other subjects as my title suggests: Tips, Information and Other Stuff.

5. What´s the goal of your blog?
Again, just being able to help people. If I help just one person, it will bring satisfaction and a sense of accomplishment.

6. Choose one word to describe your blog?
Hmmm…that’s tough…..Informative

7. What kind of people read your blog and who should read it? How are their reactions?
Honestly, I don’t know the answer to your first question. Definitely Home Owners wanting to sell their homes without using a Realtor. I am willing to teach and support them and show them the other options they have (and might not know about) I’ve had a few positive comments and even been called an “inspiration”, but my blog is new.

8. Are there any posts you are excited to offer?
All the posts I’ve written I’ve been excited about because I thought they brought useful information to people….Home Owners, Pet Owners and others. The short post about the books, The Secret and Your Hearts Desire is really something I think more people should learn about and consider adapting into their own lives.


I have another blog over at SQUIDOO. Can I plug that?! There’s a post offering more in depth information to the FSBO (for sale by owner) I will incorporate a portion of that post to Tips, Information and Other Stuff soon.
There’s also a special free offer from me to the FSBO coming soon, I guess you’ll have to visit often so you don’t miss out.

9. Which of your blog posts had the most reactions from your readers?
The post about The Secret

10. The top 3 blogs you read?
I really haven’t had the time to enjoy other blogs right now. But I do receive emails from the below two blogs.
Real Estate News and Tips for New Home Buyers
BLoG ABoUT MoNEY oNLINE
And mine
http://www.acassociatesusa.blogspot.com/

11. Is there anything you want to say at least?
I am open to any suggestions or comments someone might have and I am very willing to help someone if needed regarding selling their home, mortgage or business note, structured settlement or other cash flow.

Your Website: acassociatesusa.com

Blog URL: http://www.acassociatesusa.blogspot.com/
www.squidoo.com/ASuccessfulFSBO

Your e-mail : andrea@acassociatesusa.com

Thank you very much for spending your time for this interview. Please send me a picture or a avartar that I can publish with your interview.

I will inform you when you can see this interview on my site.
Best regards
Halil

Digg!

Sunday, April 8, 2007

FSBO: USING MLS LISTINGS

Multiple Listing Service

Multiple Listing Service (MLS) (also Multiple Listing System or Multiple Listings Service) is a database which allows real estate brokers representing sellers under a listing contract to widely share information about properties with real estate brokers who may represent potential buyers or wish to cooperate with a seller's broker in finding a buyer for the property.

The MLS combines the listings of all available properties that are represented by brokers who are both members of that MLS system and of NAR or CREA, (the National Association of Realtors in the US or the Canadian Real Estate Association).

The purpose of the MLS is to enable the efficient distribution of information so that, when a real estate agent is introduced to a potential home buyer, he/she may search the MLS system and retrieve information about all homes for sale in a given area or price range, whether under a listing contract by that agent's brokerage or by all participating brokers.

The MLS systems are governed by private entities, and the rules are set by those entities with no state or federal oversight, beyond any individual state rules regarding real estate. MLS systems set their own rules for membership, access, and sharing of information, but are subject to nationwide rules laid down by NAR or CREA. An MLS may be owned and operated by a real estate company, a county or regional real estate Board of REALTORS or Association of REALTORS, or by a trade association. Membership of the MLS is generally considered to be essential to the practice of real estate brokerage.

Limitations of access to the MLS:
Most MLS systems restrict membership and access to real estate brokers (and their agents) who are appropriately licensed by the state (or province); are members of a local Board or Association of REALTORS; and are members of the trade association (e.g., NAR or CREA).

A person selling his/her own property - acting as a For Sale By Owner (or FSBO) - cannot put a listing for the home directly into the MLS. Similarly, a properly licensed broker who chooses to neither join the trade association nor operate a business within the associations's rules, cannot join the MLS.

However, there are brokers and many online services which offer FSBO sellers the option of listing their property in their local MLS database by paying a flat fee or another non-traditional compensation method. This may be the fastest growing segment of the real estate industry.

MLS LISTING OPTIONS:

Flat Fee Listings

FSBO Support

Homes By Owner


Enter ForSaleByOwner.com


Buy and Sell Real Estate Without Paying a Broker!

A Useful Link for anyone selling or thinking about selling their property:
Get your homes value for free

Wednesday, April 4, 2007

What are Owner Financed Mortgages?

I mentioned Owner Financing in my last post and want to take time to explain further how this can truly benefit Home Owners.

Owner-Financed Mortgages, also are known as seller-carry back mortgages. They're created when a seller of a home decides to "carry" a mortgage note from the purchaser of his or her home.

This is usually done when the property is difficult to sell or when the buyer cannot obtain traditional financing from a bank. This might happen because the buyer has had bad credit or a blemish on his credit report, "too much debt" or maybe because the property is in a rural location with a lot of land (banks typically don't like to lend on these types of properties).

There are literally billions of dollars of owner-financed mortgages in circulation at any given time. Owner Financing has been in existence for decades and is becoming more and more common today because of the growing numbers of individuals who fail to qualify for a traditional loan from a bank or mortgage company. Banks are also becoming more conservative in their lending practices.

These factors prevent millions of families from being able to obtain home loans, reducing the number of potential home buyers. With this in mind, home sellers sometimes choose to offer owner financing in order to sell their homes faster. They request a down payment (generally 5% - 10%) and the interest rate is higher than market rates. Of course the agreement between the seller and buyer is negotiable in terms, so the buyer is able to purchase the home.

Why Should A Home Seller Offer Owner Financing?
It's challenging when a person decides to sell a house. Sellers frequently face a limited time period to make a sale. Jobs, transfers, debts, moves and changes in our lives create serious needs.

Sometimes market conditions are not good for getting what the seller wants. Of course, there are interested buyers. They may have the funds for a down payment, but the problem might be securing a traditional loan. Offering Owner Financing opens the doors for many buyers who get turned down by the banks.

Immediately after the home is sold with Owner Financing, the seller is satisfied because the property was sold quickly and receiving a good return on their investment.
As time passes though, the mortgage note holder might decide that having a lump sum of cash would be better than waiting years to collect the balance, usually one month at a time.

The seller would than contact a Contract Buyer, also known as a Note Purchaser, who would help them cash out their note.
TAKE NOTE: If the seller wishes not to carry the note at time of sale, a contract buyer can purchase the note at time of closing for cash, which is known as Simultaneous Closing (see previous post)
There are many good reasons for an individual wanting to cash in their note.
Some are:
A) Becoming debt free or Consolidating debt, including high interest credit cards
B) Paying for their children's college education
C) Taking an exotic vacation or purchasing other luxuries
D) Purchasing a new home or second home
E) Other investment opportunities
F) Medical care
G) Or simply, just storing away a lump sum of cash received

The benefits of offering Owner Financing can put you in a winning financial position.
The contract secured by your house, is worth thousands of dollars in a lump sum of cash. It doesn't' matter if it's a new contract or one that's had some payments made. Each one has it's own characteristics that gives it cash value. Based on your needs, a Contract Buyer can tailor unique purchase plans that you can benefit from.

Here's two examples on a house which sold for $100,000.00

Example one:
Selling price.......................$100,000
Down Payment .......................$ 21,000
Remaining balance amortized 2o yrs.............$79,000
Interest Rate .........................10%
Monthly Payment ........................$762.37
48 payments have been made totalling....$36,593.76
Current Balance on Principal Owed..............$72,890.71

The contract buyer offers $63,500 CASH

The Seller has received a total of $121,093.76 Not bad for a house selling for $100,000

Example Two: Selling Part of Your Contract:
Selling Price.......................................$100,000.00
Seller Received 48 Payments ........................$ 36,593.76
Contract Buyer Purchases the next 60 payments.......$ 34,500.00

Total Cash to Seller so far.........................$ 92,093.76

After 60 payments, the Contract is returned to the
Home Seller with a balance of ...................... 60,892.03

When you add the total cash to the seller, plus the remaining balance after 60 payments, it totals $152,985.79 AND, don't forget the interest they'll earn on the remaining balance. Remember, the house sold for $100,000.00

Selling part of a contract can be very profitable.

Offering Owner Financing can be a win-win situation for everyone involved. It can be financially beneficial and the possibilities are endless.

If you would like more information, please fell free to get in touch with me. I will teach you the options and guide you along the way. FOR SALE BY OWNER

Sunday, April 1, 2007

PART II - Getting your House Ready For Sale

I wanted to give you more information regarding how to be successful when selling your home without using a Realtor.

Get The Word Out:
The first thing to do is put up a sign in the front yard. Tell your neighbors. They may already know of someone looking in the area, maybe even a family member. Let people know where you work, a church group or club. If you want to go further, put up notices on bulletin boards. Last but not least, run a classified ad.

Showing Your Home:
When you have an appointment to show your home, open the windows and air out before any potential buyer arrives. This will get rid of any last minute unpleasant odors that might be lingering. It's always a good idea to have the scent of pleasant aromas in the house. Things like fresh bread,cookies, the smell of cinnamon or vanilla.

Open House:
An open house can be very effective in promoting your house.
For Two reasons:
1)You can schedule the open house at a specific time and day and you'll be attracting a lot of people at the same time.
2)This creates a spirit of competition. Competition produces action that ends up with a sale.

Place a welcome sign in your front yard or by the front door.
For security reasons, I would recommend having visitors sign in before they go through your home.
Have a information circular or flyer on your home that visitors can take with them. The information flyer is good for people who call on your newspaper ad. You can take their address and even mail one to them.

The information flyer should include: Your name, address and phone number. Sales Price and if you're offering OWNER FINANCING (more on this in my next post)the down payment you're requesting. Mention you'll consider all offers in writing, with the understanding you won't take the home off the market until a legally binding sales contract has been signed and earnest deposit money is deposited with your attorney.
Respond to all offers and if they are too low, counter the offer.

Your information flyer should also include:Property taxes, insurance and utilities etc..and remember to list the features of your house:
Square footage, type of roof and age, kind of heat, air conditioning, schools, kind of water heater and age, the lot size, describe the structure, electrical system, bathrooms and kitchen, the rooms size and measurements and public transportation available.

Tell a little about the outdoor features and anything else you feel is unique about the home.
List any recent repairs or maintenance. When was it last painted or sided, new roof etc.
Have pictures on display during different seasons of the year. If you're showing your home during the fall or winter, show pictures during spring or summer. The pictures will show the flowers and plants in bloom.

Schedule your open house during peak hours when traffic goes by your house. Put a sign up where people will see your sign as they drive by.

Some helpful links: Visit their sites for more information
ForSaleByOwner
HomesByOwner
Owners.com

Recommended Reading:
How To Sell Your Home Fast in Good or Bad Markets


ss_blog_claim=d8fa872d2bd6cfcebf9ecb17a75c07c9